Reverse mortgages · Homeowners 62+
Stay in the home you love. Let its equity work for you.
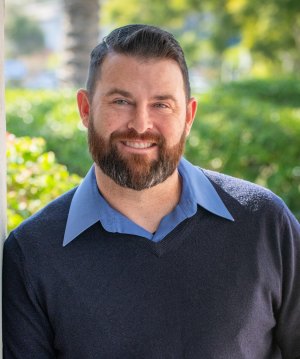
I’m Sean Harrison, a reverse mortgage specialist with C2 Financial. One unhurried conversation tells you whether a HECM or a jumbo reverse mortgage fits your home, before you fill in a single application.
No monthly mortgage payment is required. You still pay property taxes, homeowners insurance and any HOA dues, and keep the home maintained.
- Reverse mortgage specialist since 2016
- Marine Corps veteran
- HECM & jumbo options
- Family members welcome
What a reverse mortgage can do
Turn home equity into cash, without selling
For many homeowners, most of their savings is the house. A reverse mortgage lets you use part of that equity while you keep living there.
Pay off an existing mortgage
The reverse mortgage pays off what you still owe, so that monthly mortgage payment stops. You still pay property taxes, insurance and HOA dues.
Add to monthly income
Take money as monthly payments, a lump sum, or a line of credit you draw on when you need it.
Plan with your family
Cover home repairs or care at home, or keep a reserve, with your children in the conversation from the start.
Options
The right program for your home
HECM
The most common reverse mortgage, insured by the Federal Housing Administration (FHA), for homeowners 62 and older.
About HECM loans →Jumbo reverse mortgage
Private programs for higher-value homes, which can reach more of your equity than a HECM allows.
About jumbo loans →HECM for Purchase
Buy your next home, perhaps closer to family or on one level, with no monthly mortgage payment afterwards.
Buying a home →How it works
Three steps, no pressure
Answer five questions
A short form, no credit check. It tells us whether a conversation is worth your time.
Talk it through with Sean
A 30–45 minute call at a time you choose. Bring a family member if you like.
Decide with every number in front of you
What you could receive, what it costs and what you keep paying, in writing, before anything is signed.
Who you’ll talk to
Sean Harrison
Sean has specialised in reverse mortgages at C2 Financial since 2016, working with homeowners and the financial advisors who help them plan retirement.
He’s a Marine Corps veteran and a USC graduate, and he’s known for explaining reverse mortgages plainly, with dignity and no pressure. Licensed in California, Oregon, Washington and Tennessee.
NMLS #1275351 · CA DRE #02205522
Common questions
What is a reverse mortgage?
A loan for homeowners 62 and older that turns part of your home’s equity into cash, while you keep living in the home and keep the title. Instead of you paying the lender each month, the loan balance grows over time and is repaid when you sell, move out for good, or pass away.
Do I still own my home?
Yes. The title stays in your name. The lender holds a lien, the same as with a regular mortgage.
Will I have a monthly mortgage payment?
No monthly mortgage payment is required. You still pay property taxes, homeowners insurance and any HOA dues, and keep the home maintained. You can choose to make payments toward the loan if you want to, but you don’t have to.
Who qualifies?
For a HECM, the youngest borrower must be 62 or older, the home must be your primary residence, you need enough equity, and property taxes and insurance must be current. You’ll also meet with a HUD-approved counselor before applying. Private (proprietary) programs have their own rules; Sean offers them from age 55 when every owner is 55 or older, in all four states he serves.
What happens to my home when I pass away?
Your heirs can keep the home by paying off the loan (often by refinancing), or sell it and keep any equity left after the loan is repaid. With a HECM, neither you nor your heirs will owe more than the home is worth when it’s sold.
Do both of us have to be 62?
For a HECM, the youngest borrower on the loan must be 62. If your spouse is younger, they may still be able to stay in the home as an eligible non-borrowing spouse, with protections that apply. Private programs can start at 55 when every owner is 55 or older. Sean will walk through how it works for your situation.
See if a reverse mortgage could work for you
Five quick questions, no credit check. If it looks like a fit, Sean reaches out personally.